Europe’s Stablecoin Debate Is Far From Settled
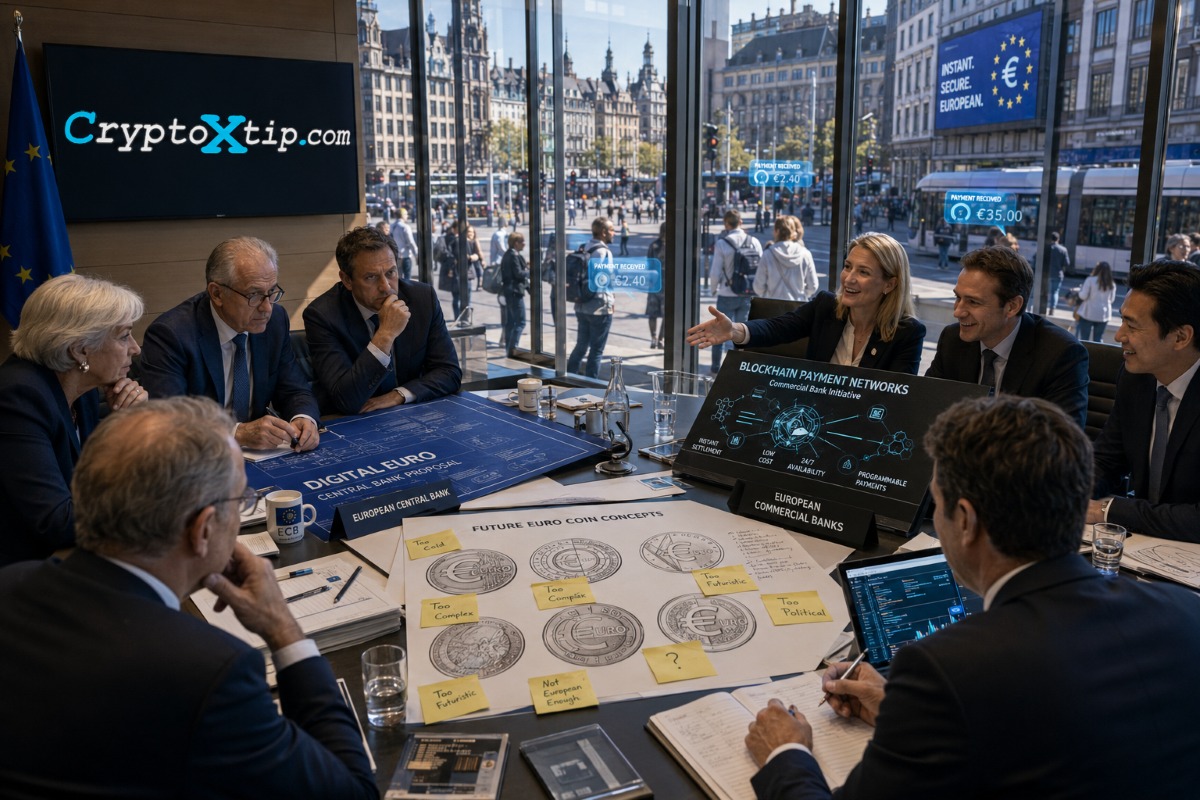
The ECB remains cautious about euro stablecoins while European banks accelerate digital payment token projects, creating a growing divide over money’s future.
Europe is entering a curious phase of its digital asset journey. Regulators have spent years building one of the world's most comprehensive crypto frameworks, yet a fundamental debate remains unresolved: who should control the next generation of digital money?
That question sits at the center of ongoing discussions surrounding euro-denominated stablecoins, tokenized deposits and digital payment assets across the European financial system.
While the European Union's Markets in Crypto-Assets (MiCA) framework has established a regulatory path for stablecoin issuers, the European Central Bank continues to express reservations about the broader role privately issued digital currencies could play within Europe's monetary system. At the same time, commercial banks across the continent are moving in the opposite direction, expanding initiatives focused on tokenized deposits, blockchain-based settlement systems and digital payment infrastructure.
The result is a growing divergence between public-sector caution and private-sector experimentation. Neither side is necessarily opposing innovation. They simply appear to have different visions of where innovation should ultimately lead.
In many ways, the debate has evolved beyond cryptocurrency. It now concerns the future architecture of money itself.
The ECB's Continuing Skepticism
The European Central Bank has maintained a consistent position regarding privately issued digital currencies, particularly those designed to function as large-scale payment instruments.
ECB officials have repeatedly argued that widespread adoption of stablecoins could introduce risks related to monetary sovereignty, financial stability and payment system fragmentation. Those concerns have become a recurring theme in speeches, policy papers and consultations surrounding digital finance initiatives throughout Europe.
From the ECB's perspective, money performs a unique public function. Allowing private issuers to gain significant influence over digital payments could potentially weaken central bank oversight of monetary flows and settlement infrastructure.
The concerns are not entirely theoretical.
The rapid global expansion of dollar-backed stablecoins has demonstrated how digital assets can achieve substantial market penetration outside traditional banking systems. European policymakers have observed this trend carefully, particularly as U.S. dollar stablecoins continue to dominate global crypto trading, decentralized finance activity and cross-border settlement.
For some central bankers, the growing influence of privately issued digital currencies raises uncomfortable questions about the future role of sovereign currencies in digital markets.
The ECB's proposed digital euro initiative has often been presented as a response to those concerns. Supporters argue that a central bank digital currency could preserve public access to sovereign money in an increasingly digital economy while reducing dependence on private payment providers.
Critics, however, question whether consumers and businesses actually need another digital payment option when existing systems already function effectively across much of Europe.
Commercial Banks See Opportunity
While regulators debate long-term monetary implications, European banks are increasingly focused on practical applications.
Several major banking groups have expanded efforts involving tokenized deposits, blockchain-based settlement mechanisms and digital payment tokens designed for institutional and commercial use cases.
Unlike traditional stablecoins, many of these projects focus on regulated bank-issued liabilities rather than standalone crypto assets. The distinction matters.
Banks argue that tokenized deposits can combine blockchain efficiency with existing regulatory protections, creating digital payment instruments that operate within established financial frameworks.
For financial institutions, the attraction is obvious.
Cross-border settlement remains expensive, fragmented and often slower than modern digital commerce demands. Tokenized payment systems promise faster transfers, programmable settlement and improved operational efficiency without requiring a complete redesign of existing financial infrastructure.
The emergence of wholesale blockchain settlement networks has further accelerated experimentation. Financial institutions increasingly view distributed ledger technology not as a threat to banking but as a potential upgrade to underlying market infrastructure.
The irony is difficult to miss. A decade ago, much of the crypto industry's narrative focused on disrupting banks. Today, some of the largest blockchain initiatives in Europe are being built by banks themselves.
MiCA Creates a New Regulatory Environment
The implementation of MiCA has significantly altered the landscape for digital assets across the European Union.
For the first time, stablecoin issuers have access to a comprehensive regulatory framework governing issuance, reserves, disclosures and operational requirements. Supporters view the framework as a competitive advantage that could attract compliant digital asset businesses to European markets.
At the same time, MiCA imposes strict obligations on issuers of asset-referenced tokens and electronic money tokens. These requirements are designed to limit systemic risks and ensure that stablecoin operators maintain sufficient safeguards.
The framework has effectively shifted the conversation from whether stablecoins should exist to how they should be regulated.
Yet regulation alone does not resolve deeper policy disagreements.
Some policymakers remain concerned that successful euro stablecoins could eventually compete with traditional bank deposits or create alternative payment ecosystems operating outside conventional financial channels.
Others argue that Europe risks falling behind global competitors if it becomes overly restrictive while digital asset infrastructure continues expanding elsewhere.
The tension reflects a broader challenge facing regulators worldwide. Encouraging innovation and preserving stability often sound compatible in principle. In practice, they frequently pull policy in different directions.
The Dollar Problem Lurks in the Background
Much of the European stablecoin discussion ultimately returns to one issue: dollar dominance.
Most global stablecoin activity remains concentrated in U.S. dollar-denominated assets. These tokens have become critical infrastructure across crypto trading, decentralized finance and international transfers.
European policymakers recognize that a purely defensive approach may not reverse this trend.
If euro-denominated digital assets fail to gain meaningful adoption, the continent could become increasingly dependent on payment instruments tied to foreign currencies and foreign issuers.
That possibility creates a strategic dilemma.
Restricting euro stablecoins may reduce certain financial stability concerns, but it could also limit the development of euro-based digital payment ecosystems. Encouraging innovation, on the other hand, introduces new regulatory and supervisory challenges.
Neither option offers a perfect outcome.
The debate increasingly resembles a balancing exercise between control and competitiveness. Central banks naturally prioritize control. Markets tend to reward competitiveness.
Institutional Adoption Continues Growing
Despite policy disagreements, institutional interest in blockchain-based settlement infrastructure continues expanding across Europe.
Banks, asset managers and financial market operators are exploring tokenized bonds, digital securities and programmable payment systems capable of supporting automated transactions.
Many of these initiatives rely on digital cash equivalents to facilitate settlement. Whether those instruments take the form of stablecoins, tokenized deposits or central bank digital currencies remains one of the central questions shaping the sector's future.
Industry participants increasingly argue that tokenization cannot reach its full potential without efficient on-chain payment mechanisms.
A tokenized bond may be innovative, but someone still needs to pay for it.
The convergence of traditional finance and blockchain infrastructure is gradually shifting from experimentation toward implementation. As covered in additional ecosystem coverage from Article Partners
That transition places greater urgency on policy decisions that may have seemed theoretical only a few years ago.
A Debate That Extends Beyond Crypto
The ongoing disagreement between the ECB and commercial banks should not be viewed simply as a dispute about stablecoins.
It reflects a larger conversation about who controls financial infrastructure in the digital age.
Central banks seek to preserve monetary stability and public trust. Commercial institutions seek efficiency, innovation and competitive advantages. Technology providers continue building tools that make entirely new financial models possible.
These objectives are not mutually exclusive, but they are not always perfectly aligned either.
The coming years will likely determine whether Europe develops a thriving ecosystem of regulated digital payment assets, leans more heavily on a future digital euro, or ultimately adopts a hybrid model incorporating elements of both approaches.
The market appears to be moving faster than the policy debate. That has become a recurring theme across financial innovation throughout history.
What This Means
Europe's stablecoin debate is entering a more consequential phase as regulatory frameworks mature and institutional blockchain adoption accelerates. The ECB remains cautious about privately issued euro stablecoins, citing concerns over monetary sovereignty and financial stability.
Commercial banks, meanwhile, are expanding tokenized payment and settlement initiatives that could reshape how money moves across financial markets. Their growing investment suggests that blockchain-based payment infrastructure is increasingly viewed as a practical business opportunity rather than a speculative experiment.
For investors, financial institutions and digital asset companies, the outcome matters far beyond cryptocurrency markets. The decisions made today will help determine who issues, controls and settles digital money across Europe's financial system in the years ahead.
Related Articles
More stories you may want to explore.


Sponsored Placements