Poland’s Crypto Veto Deepens MiCA Uncertainty
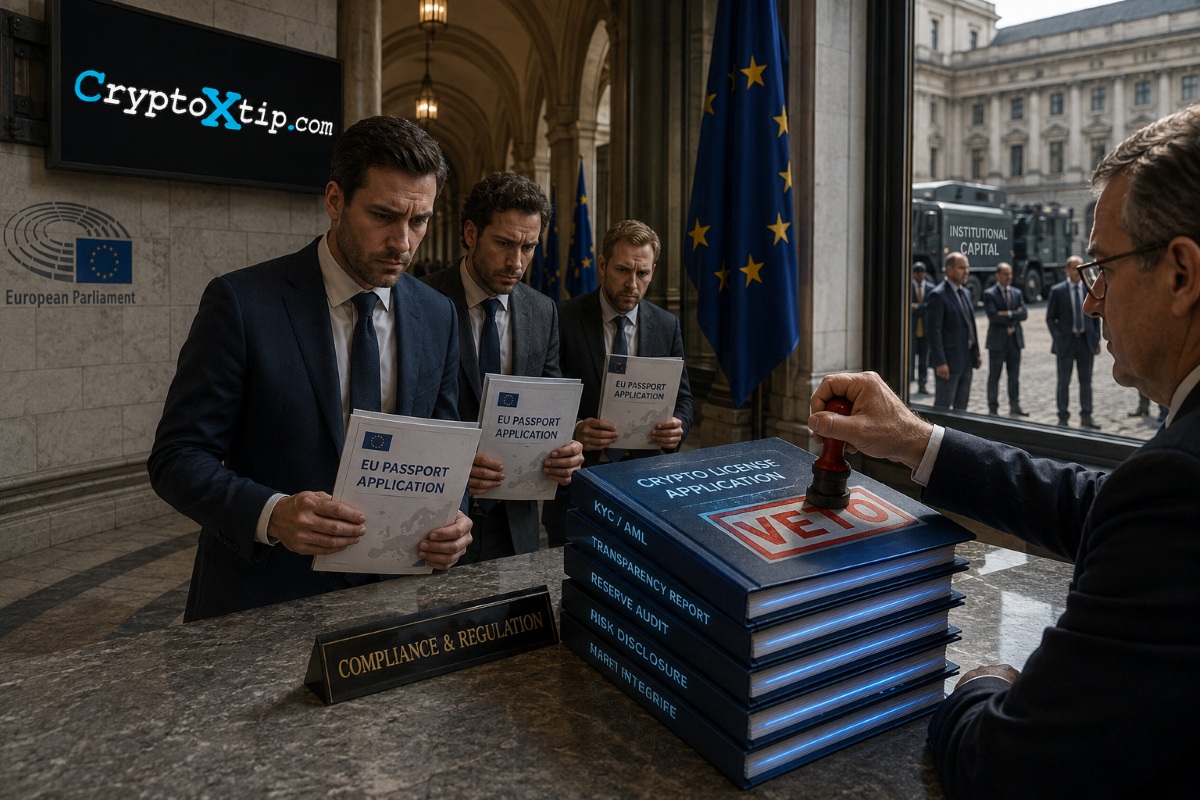
Poland’s third crypto bill veto complicates MiCA implementation, adding another layer of regulatory caution for investors already watching the U.S.
Poland’s attempt to bring its crypto market fully into line with European Union rules has hit another presidential wall. President Karol Nawrocki has vetoed the country’s crypto regulation bill for a third time, extending a legislative standoff that is becoming less of a procedural delay and more of a market signal.
The blocked bill was designed to implement the EU’s Markets in Crypto-Assets framework, known as MiCA, into Poland’s domestic supervisory system. MiCA is already the central crypto rulebook across the European Union, covering issuers, exchanges, custodians and other crypto-asset service providers. But European regulation still needs national machinery: local supervisors, licensing processes, enforcement powers and legal procedures that companies can actually follow.
That is where Poland remains stuck. The veto means crypto firms operating in or from Poland still face uncertainty over how domestic licensing and supervision will work. For an industry that claims to enjoy decentralization but still needs bank accounts, legal opinions and compliance officers, uncertainty is not a lifestyle choice. It is a cost.
Nawrocki’s objection centers on the view that the legislation failed to address earlier concerns. Previous disputes around the bill included fears of excessive administrative burdens, broad enforcement powers and rules that could push smaller Polish firms abroad rather than bring them into a clear regulatory perimeter.
Poland’s MiCA Problem Is Now a Market Problem
The irony is that MiCA was supposed to reduce fragmentation across Europe. In theory, the framework gives crypto companies a clearer route to authorization and allows licensed firms to serve clients across the bloc through passporting. In practice, national implementation still matters. A passport is useful only after someone has issued it.
For Polish crypto firms, the delay creates an uneven playing field. Companies in jurisdictions with functioning MiCA licensing regimes can move ahead, while domestic platforms may face slower approvals, unresolved supervisory expectations and higher legal risk. Larger players can shop for regulatory homes across Europe. Smaller firms usually cannot treat legal relocation like changing a coffee supplier.
That asymmetry matters for users as well. A lack of domestic clarity does not make crypto activity disappear. It can push trading, custody and token services toward foreign entities, offshore platforms or less transparent arrangements. Regulators often dislike this outcome, though regulatory gridlock has a habit of manufacturing it.
Supporters of stricter rules argue that Poland needs a robust framework to protect users, reduce fraud and give supervisors the tools to police a market with a long memory of collapses, hacks and promotional nonsense dressed up as financial innovation. Critics argue that the Polish proposals have leaned too heavily toward bureaucracy and enforcement power, risking a regime that protects consumers partly by making local innovation too expensive to attempt.
Regulation Is Becoming a Liquidity Question
For traders and investors, the Polish veto is not only a local political story. It fits a broader pattern: crypto markets are increasingly being shaped by regulatory geography. Capital prefers venues where rules are clear, enforcement is predictable and counterparties can explain their legal status without producing a 90-page memo and a nervous smile.
Liquidity follows confidence. If market makers, custodians and institutional investors cannot assess licensing risk, they price that uncertainty into spreads, access and exposure limits. Retail traders may see the issue as distant legal theater, but legal theater has a way of showing up later as fewer banking partners, tighter onboarding rules or restricted product access.
The European Union still has a stronger claim to regulatory clarity than many major markets. MiCA offers a single framework, especially compared with the patchwork that has defined crypto oversight elsewhere. Yet Poland’s repeated veto shows that even a harmonized regime can become uneven when national politics meets a fast-moving industry.
This is especially relevant as the MiCA transition period approaches its final stage. Firms that were already operating under previous national regimes face deadlines for obtaining proper authorization. In countries where the process is functioning, that is a difficult but manageable compliance exercise. In countries where domestic implementation remains unresolved, it becomes a strategic headache.
The result is not necessarily a crypto exodus from Poland. It is more likely a slow sorting process. Serious firms will look for the safest regulatory route, even if that means licensing elsewhere in the EU. Less serious firms may exploit confusion until supervisors catch up. Users, as usual, will be left to distinguish between compliance strategy and regulatory fog.
The U.S. Still Has Its Own Uncertainty Premium
Poland’s difficulties arrive while institutional investors continue to watch the United States for clearer crypto rules. The U.S. market has made progress in some areas, including more structured debate around market structure, stablecoins and the division of authority between securities and commodities regulators. But the larger question remains unresolved: which digital assets are securities, which are commodities and which belong in the regulatory drawer labeled “please stop asking until Congress votes.”
That uncertainty continues to influence institutional behavior. Large investors do not need perfect rules, but they do need rules that can be modeled. Ambiguous enforcement risk makes position sizing harder, product launches slower and compliance committees more powerful than portfolio managers would prefer.
This is one reason the institutional crypto trade has become more selective. Bitcoin and certain highly liquid assets benefit from deeper infrastructure, clearer narratives and broader acceptance. Smaller tokens face a tougher environment, especially when their legal status, exchange access or issuer obligations remain unclear. In a market where liquidity can vanish quickly, regulatory doubt is not background noise. It is part of the risk premium.
The U.S. debate also affects Europe. Global exchanges, custodians and asset managers do not build compliance programs in isolation. A firm serving clients across the U.S., EU and other major markets must manage overlapping requirements. When one major jurisdiction remains unsettled, it slows product design everywhere else.
That does not mean regulation is bearish by default. The opposite may be true over longer horizons. Clear rules can support institutional adoption, improve custody standards and reduce the reputational discount that still hangs over parts of the sector. But unclear rules are different. They combine the costs of regulation with few of its confidence benefits, which is a remarkably efficient way to annoy both innovators and supervisors.
Investors Are Learning to Price Legal Risk
Investor sentiment toward crypto regulation has matured. In earlier cycles, almost any government action was treated as either an existential threat or a validation parade. Today, markets are more discriminating. Traders ask whether a rule improves access, restricts liquidity, clarifies custody, limits leverage or shifts activity to competitors.
In Poland, the immediate implication is continued caution. Domestic firms may delay expansion, seek licensing in other EU jurisdictions or wait for a revised bill that can survive the presidency. International platforms may view Poland as a market to serve through passporting rather than local infrastructure. Users may face a slower path toward fully supervised domestic services.
For policymakers, the lesson is blunt. Crypto regulation has to be strict enough to matter and workable enough to use. A law that looks impressive on paper but cannot win political support or industry cooperation may become another exhibit in the museum of well-intentioned financial plumbing.
The Polish case also shows why regulatory competition inside Europe has not disappeared under MiCA. Countries with efficient licensing systems and credible supervisors may attract more crypto businesses. Those stuck in political conflict may watch activity migrate elsewhere while still carrying the reputational burden of an underregulated market.
For broader ecosystem watchers, including readers following Crypto X Tip coverage, the story is less about one veto and more about the next phase of crypto regulation: execution. Passing frameworks is hard. Making them usable is harder.
What This Means
Nawrocki’s third veto keeps Poland in a difficult position at a sensitive moment for European crypto regulation. MiCA is meant to create clarity, but Poland’s domestic process now risks creating the opposite for local firms and users.
The market impact is unlikely to come through sudden price moves. It is more likely to appear through business decisions: where exchanges apply for licenses, where custodians invest, where startups incorporate and where institutional investors feel comfortable deploying capital.
For investors, the message is familiar but important. Regulatory clarity is becoming part of crypto’s infrastructure, just like liquidity, custody and security. Markets can trade through uncertainty for a while, but serious capital eventually asks boring questions. In finance, boring questions often decide where the money goes.
Related Articles
More stories you may want to explore.


Sponsored Placements