Stablecoins Quietly Become DeFi’s Main Product Again
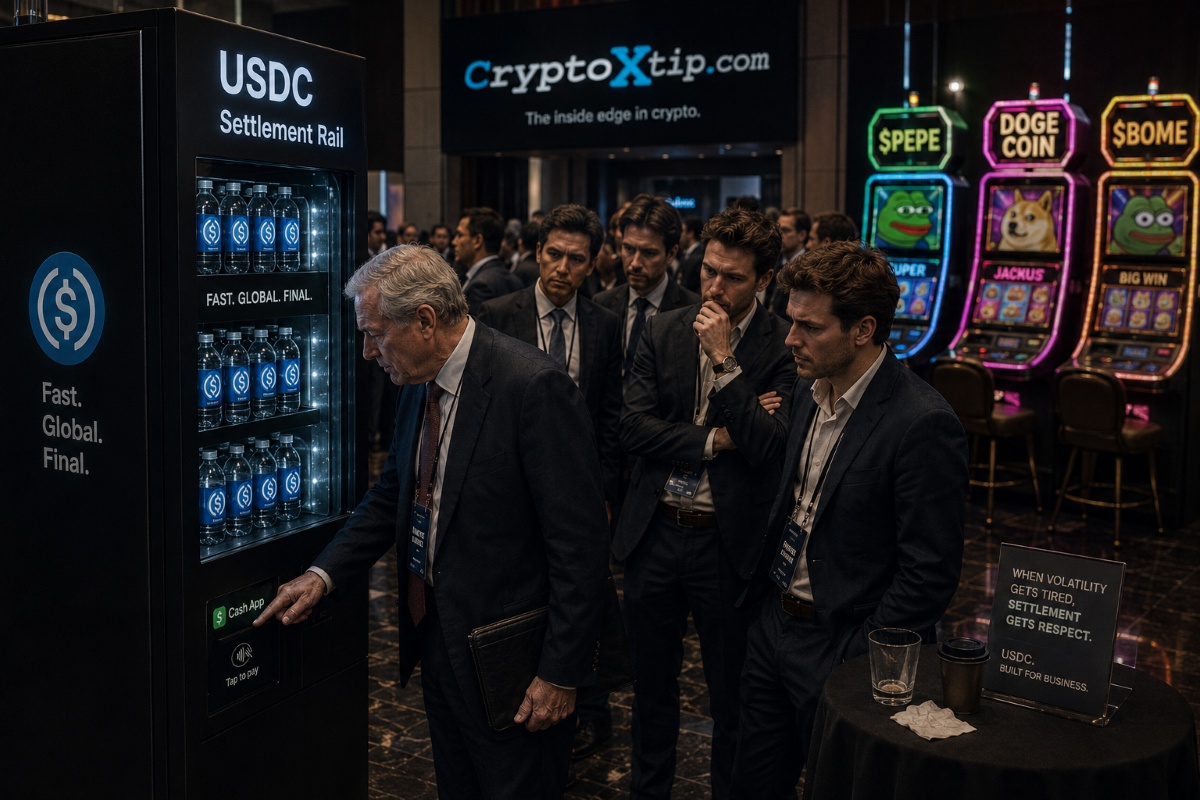
USDC is expanding beyond crypto trading as Cash App begins rolling out stablecoin support, pushing DeFi closer to mainstream payments.
For years, decentralized finance promised to rebuild payments, lending and global money movement on blockchain rails. Then came the speculative phase: memecoins, leverage loops, yield farming incentives and enough token emissions to make central bankers reach for aspirin.
Now the industry appears to be circling back to the one crypto product ordinary users actually understand almost immediately: digital dollars.
Stablecoins have once again become the center of gravity inside DeFi, and this time the momentum looks less dependent on speculative trading cycles and more tied to payment infrastructure. Circle’s USDC continues expanding across financial platforms, while Block’s Cash App has begun gradually rolling out stablecoin functionality tied to USDC for its massive user base.
That shift matters because stablecoins are no longer behaving like a side utility for crypto traders. Increasingly, they are becoming the infrastructure layer itself.
Recent reporting from CoinDesk and Fortune indicated that Cash App’s stablecoin integration would allow users to deposit and withdraw USDC while using blockchain rails largely in the background. The product direction appears intentionally pragmatic rather than ideological. Crypto finally discovered that consumers prefer “money that works” over philosophical debates about monetary sovereignty at breakfast.
Stablecoins Move From Trading Tool to Financial Rail
The modern stablecoin market was originally built around crypto exchange liquidity. Traders needed dollar exposure without leaving blockchain ecosystems, and stablecoins solved that problem efficiently. USDT dominated globally, while USDC positioned itself as the more institutionally aligned alternative with greater emphasis on compliance, reserve transparency and regulated partnerships.
That distinction is becoming increasingly important as regulators, banks and payment firms move closer to integrating blockchain-based settlement systems into mainstream financial products.
Circle has spent the past two years aggressively pushing USDC beyond exchange activity and into payments infrastructure. Partnerships with financial service providers, fintech firms and payment processors have steadily expanded the stablecoin’s reach. The company has repeatedly framed stablecoins less as crypto assets and more as programmable internet-native dollars.
The language may sound polished enough to survive a boardroom presentation at a Fortune 500 conference, but the underlying trend is real. Stablecoins increasingly function as settlement rails rather than speculative instruments.
Cash App’s gradual rollout is especially notable because of scale. The platform reportedly serves tens of millions of active users, many of whom are not traditional crypto participants. Integrating USDC into a consumer-facing payment application potentially exposes stablecoins to a demographic that has little interest in navigating decentralized exchanges or managing complicated wallets.
That distinction could define the next phase of adoption.
Why DeFi Needed Stablecoins Again
DeFi spent much of the past cycle struggling with an uncomfortable reality: volatility is exciting for traders but terrible for financial infrastructure.
Protocols built entirely around speculative assets often faced collapsing collateral values, liquidity fragmentation and unstable user behavior during market downturns. Stablecoins became the anchor asset that kept lending markets functioning even as broader crypto prices fluctuated violently.
Today, stablecoin liquidity dominates many of DeFi’s largest lending and borrowing protocols. USDC remains heavily used across decentralized lending markets, liquidity pools and yield products because institutions and sophisticated traders generally prefer lower volatility exposure while maintaining on-chain flexibility.
The irony is difficult to miss. After years of crypto arguing it would replace traditional finance entirely, one of the industry’s strongest products became a blockchain version of the U.S. dollar.
Still, stablecoins solve practical problems that traditional banking systems often handle poorly:
- 24/7 settlement
- Fast cross-border transfers
- Programmable payments
- Lower friction for global liquidity movement
- Simplified on-chain accounting for digital assets
These advantages matter far more to businesses and fintech companies than speculative token narratives. Financial infrastructure tends to reward reliability over ideology eventually, even if crypto markets occasionally forget that during bull cycles.
The Institutional Push Behind USDC
USDC’s growth has also been helped by improving regulatory clarity in several jurisdictions. In Europe, MiCA regulations established clearer operational standards for stablecoin issuers, while U.S. lawmakers continue debating stablecoin frameworks that could formalize reserve and compliance requirements.
For institutional firms, regulatory clarity matters almost as much as technological efficiency. Large payment providers and financial companies rarely move aggressively into uncertain legal environments unless the potential market opportunity becomes impossible to ignore.
Circle has positioned itself carefully within that environment. The company emphasizes reserve transparency, Treasury-backed reserves and partnerships with traditional financial firms rather than anti-establishment crypto messaging.
That approach has earned criticism from some decentralized finance purists who argue that heavily regulated stablecoins create centralized chokepoints inside supposedly decentralized ecosystems.
The criticism is not entirely wrong.
USDC can be frozen under certain compliance scenarios, and centralized issuers ultimately maintain significant control over the assets they issue. From a philosophical standpoint, stablecoins like USDC are closer to tokenized fintech products than censorship-resistant cryptocurrencies.
Yet markets often prioritize convenience and trust over ideological purity. Institutional adoption rarely arrives wearing a revolutionary hoodie.
Circle’s recent expansion efforts also suggest the company sees stablecoins evolving beyond simple payments. The firm has increasingly discussed infrastructure for AI-driven transactions, automated micropayments and programmable financial services built directly on blockchain rails.
That may sound futuristic, but parts of the financial industry are already exploring machine-driven commerce where autonomous systems process small payments continuously without traditional banking delays.
Stablecoins are uniquely suited for that environment because they combine predictable pricing with blockchain-native settlement.
Cash App Could Normalize Stablecoin Usage
Perhaps the most important aspect of Cash App’s rollout is that users may not even think of it as “using crypto.”
That subtle shift could become one of the industry’s biggest milestones.
For years, crypto adoption metrics were heavily tied to trading activity, token speculation and exchange onboarding numbers. But mainstream financial technology succeeds when infrastructure becomes invisible.
Consumers do not think about ACH settlement layers while buying coffee. They care whether payments arrive quickly, cheaply and reliably.
If stablecoins begin operating quietly behind consumer applications, blockchain adoption could accelerate without users actively participating in crypto culture itself.
That scenario may frustrate parts of the crypto industry that still frame adoption around token speculation and ideological evangelism. Yet it is also probably how financial technology evolves in practice.
The internet did not become mainstream because people loved TCP/IP protocols. It became mainstream because sending emails was easier than fax machines.
Stablecoins may be entering a similar phase.
Some investors already view the trend as one of the more durable narratives in digital assets. Even during periods of broader crypto weakness, stablecoin activity often remains resilient because it supports trading infrastructure, payments and liquidity management simultaneously.
Additional ecosystem coverage from Article Partners has also increasingly focused on stablecoin-related infrastructure rather than purely speculative sectors, reflecting where institutional attention appears to be moving.
Risks Still Exist Beneath the Optimism
Despite growing adoption, stablecoins are hardly risk-free.
Regulatory uncertainty remains substantial in the United States, especially regarding reserve standards, consumer protections and yield-bearing products. Policymakers continue debating how stablecoin issuers should operate within existing banking frameworks.
Liquidity concentration also remains a concern. A handful of issuers still dominate the stablecoin ecosystem, creating systemic dependencies that could become problematic during periods of market stress.
There are also geopolitical implications. Dollar-backed stablecoins effectively expand the global reach of U.S. dollar infrastructure through blockchain networks. Some governments may welcome that liquidity. Others may eventually resist it.
Technical risks persist as well. Smart contract vulnerabilities, bridge exploits and operational failures remain part of the broader DeFi environment surrounding stablecoins.
And while stablecoins reduce volatility relative to crypto assets, they are still exposed to banking relationships, reserve management and regulatory intervention.
Crypto markets occasionally market stablecoins as “safe” simply because they avoid token price swings. Financial history suggests anything involving leverage, liquidity and human incentives deserves at least some skepticism.
What This Means
Stablecoins are increasingly becoming the practical center of decentralized finance rather than just another category within it.
USDC’s expanding integration into mainstream financial applications like Cash App reflects a broader transition happening across crypto infrastructure. The industry is gradually shifting away from purely speculative use cases toward payment systems, settlement networks and programmable financial rails.
That does not mean volatility or speculation disappear from crypto markets. They probably never will. Financial markets have always enjoyed a good casino attached to the side entrance.
But the growing role of stablecoins suggests the next phase of DeFi may depend less on chasing explosive token appreciation and more on quietly replacing outdated financial plumbing underneath existing applications.
If that trend continues, the most important crypto transaction of the next decade may not involve trading at all.
Related Articles
More stories you may want to explore.


Sponsored Placements